Global Oil Transport: Shipping Sets the Tone
Energy Markets, Supply Chains, Oil Transportation
Global Oil & Transportation Stress Watch: Why Shipping, Not Wells, Now Sets the Tone
Crude oil production has largely clawed its way back, but the cost of moving that oil has exploded. For anyone tracking energy markets or supply chain risks, the new stress point is not just how much oil the world can pump, but how reliably and affordably it can be transported, refined, and delivered.
A Growing Disconnect: Production Recovery vs. Transportation Costs
On paper, global crude supply looks surprisingly resilient. Despite near‑collapse of traffic through the Strait of Hormuz—down roughly 98% from normal levels to around one tanker a day—Middle East crude exports have been maintained near or even above pre‑war averages via alternative routes and shuttle operations, at about 18.5 million barrels per day (strategicenergymap.org).
Yet the Global Oil & Transportation Stress Watch makes clear that this production recovery masks a sharp disconnect: the physical oil is available, but the cost and complexity of refining it and moving it, crude and refined, have surged. Tanker indices have more than doubled since September, with some VLCC routes earning over $1 million per day (commodityscope.com). In other words, barrels are flowing—but at a price that reshapes trade patterns, margins, and risk models.
Rising Tanker Freight Rates and Supply Chain Planning
For supply chain planners, tanker freight is no longer a background cost; it is a central strategic variable. Shipping a VLCC from the US Gulf Coast to China in November is estimated to cost around $80 million—almost ten times pre‑war levels and close to half the value of the cargo itself (investing.com).
Such costs force refiners and traders to rethink traditional routes. Asian buyers may pivot away from US crude toward shorter‑haul Middle Eastern or Russian barrels, even if headline prices look similar. Longer voyages, war‑risk insurance, and sanctions‑related vessel shortages—over 120 VLCCs effectively sidelined by US sanctions—translate into tighter effective capacity and volatile lead times. For planners, this means building in wider delivery windows, diversifying ports of discharge, and holding more inventory to buffer against shipping shocks.
Airline Suspensions and the Hidden Strain on Jet Fuel Flows
Air transport disruptions add another layer of stress. Airline suspensions on key long‑haul routes—driven by conflict zones, higher fuel costs, and insurance premiums—do more than affect passengers. They also disrupt the logistics of high‑value, time‑sensitive goods that depend on belly cargo capacity: electronics, pharmaceuticals, and critical spare parts for energy infrastructure itself.
On the demand side, fewer flights can temporarily ease jet fuel consumption. But when suspensions are patchy and constantly changing, they complicate jet fuel demand forecasts for refiners and traders. The result is a planning puzzle: fuel producers must balance uncertain jet demand with strong diesel and gasoline pulls, while logistics teams scramble to reroute airfreight onto already‑stressed ocean and land corridors. And demand changes are often localized, which may in some cases help rebuild stocks, in others, it becomes demand destruction when duration is extended.
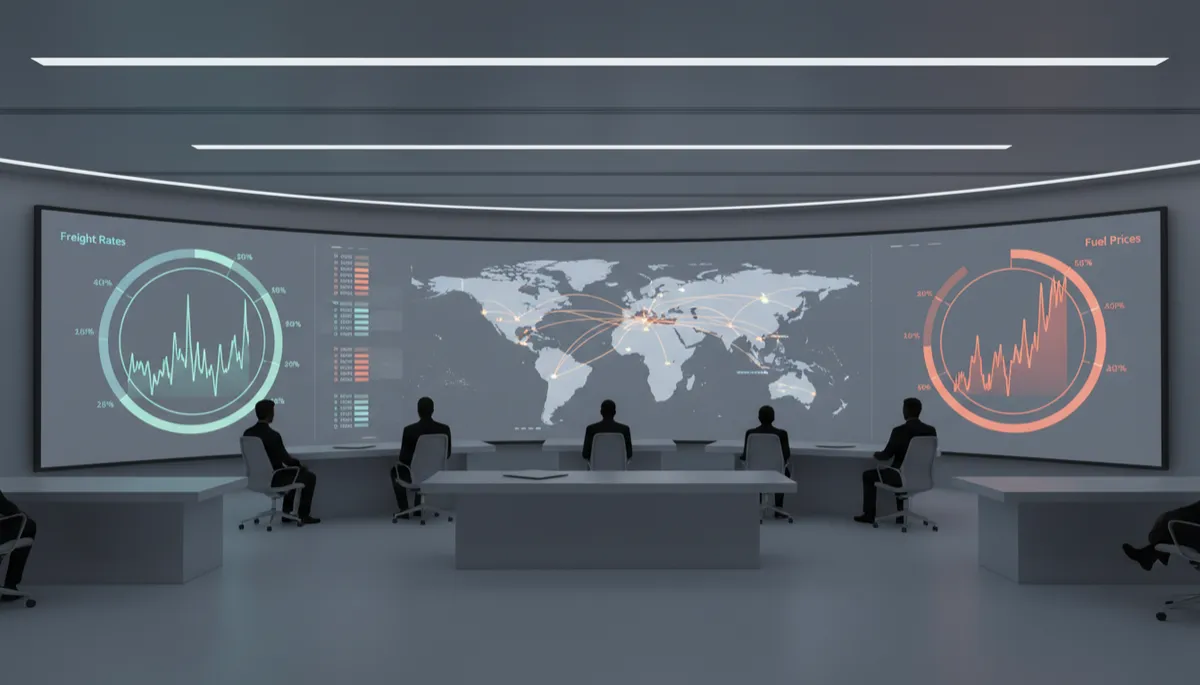
Integrated views of ships, flights, and prices are becoming core to risk-aware planning.
Refining Margins, Capacity, and the Risk of a Structural Reset
While crude can be rerouted, refined products are where the system is really straining. Product flows through Hormuz have collapsed from 3.6 million barrels per day to under 700,000, even as crude exports remain robust. This mismatch is boosting refining margins, especially for diesel and jet fuel, as regions short on local refining capacity bid aggressively for imports.
Elevated margins send a powerful signal: refinery capacity—its location, complexity, and reliability—is now as important as upstream supply. Over time, this could drive a structural market reset, with investment shifting toward coastal, flexible refineries closer to end‑demand and away from models that rely on long, vulnerable product routes. For individuals tracking energy equities or regional price spreads, understanding where new capacity is likely to be built (or shuttered) becomes a key edge.
Why Firms Must Track Transport Costs and Global Oil Stress
The current Global Oil & Transportation Stress Watch underscores three essentials for anyone interested in energy markets or supply chains:
Transportation costs now drive delivered prices and trade flows as much as headline crude benchmarks. Ignoring freight is ignoring half the story.
Refinery capacity and location determine which regions face chronic shortages, high pump prices, or sudden windfall margins when routes are disrupted.
Global oil stress indicators—from chokepoint flows and tanker attacks to inventory levels and PSC safety data—offer early warning of price spikes and supply crunches.
Whether you are an investor, supply chain professional, or simply trying to anticipate your future fuel bills, watching wells alone is no longer enough. The new fault lines run through shipping lanes, flight paths, and refinery gates—and understanding them is essential to reading where energy markets go next.
Top 3 recommended actions
1. Recalculate total delivered cost—not just fuel prices
Priority: Immediate
Reassess landed costs using diesel, jet fuel, bunker fuel, freight, insurance and security surcharges. Model three scenarios: current conditions, another 15% cost increase, and partial normalization.
Management decision: Identify products, customers and routes where margins become unacceptable, and renegotiate pricing or contracts before losses accumulate.
2. Secure alternative transportation capacity and routes
Priority: Next 7–14 days
Identify shipments dependent on disrupted maritime corridors, vulnerable airlines or single transportation providers. Establish qualified alternative routes and carriers, including their actual available capacity and cost.
Management decision: Reserve contingency capacity for critical products rather than paying to protect every shipment equally.
3. Protect critical inventory while preparing for demand destruction
Priority: Next 30 days
Segment inventory by criticality, replenishment risk and customer demand sensitivity. Increase targeted protection for essential items with long or unreliable lead times, while reducing exposure to discretionary products whose demand may weaken under sustained high prices.
Management decision: Protect continuity without creating excessive inventory that becomes expensive or obsolete if demand falls.
What to monitor by region
Region | Priority sources |
|---|---|
North America | EIA Weekly Petroleum Status Report for diesel stocks, refinery utilization and fuel production |
Europe | Eurostat for industrial output, freight and demand indicators; IEA for global product balances |
Asia / Philippines | Philippine DOE for inventories, fuel prices and import conditions; LTFRB for jeepney fares and operating relief |
The urgency is supported by today's BP report of refining margins reaching $46.70/barrel in Q3, nearly triple the year-earlier figure, and by the EIA's assessment of unusually tight diesel inventories.
My recommendation: Start with Action 1 this week. A clear view of which products, routes and customers are most exposed will tell you where to apply Actions 2 and 3 without unnecessarily increasing costs.
For my Talk Tuesday audience, the message is:
“Stop managing fuel prices. Start managing delivered cost, transportation continuity and demand risk.”
Detailed Report here; https://drive.google.com/file/d/1j791qbu7M94d66ErpgD_6ouBns2VgsjI/view?usp=sharing